top of page
Amazon Equity Research: AWS Growth vs. AI Capex Risk
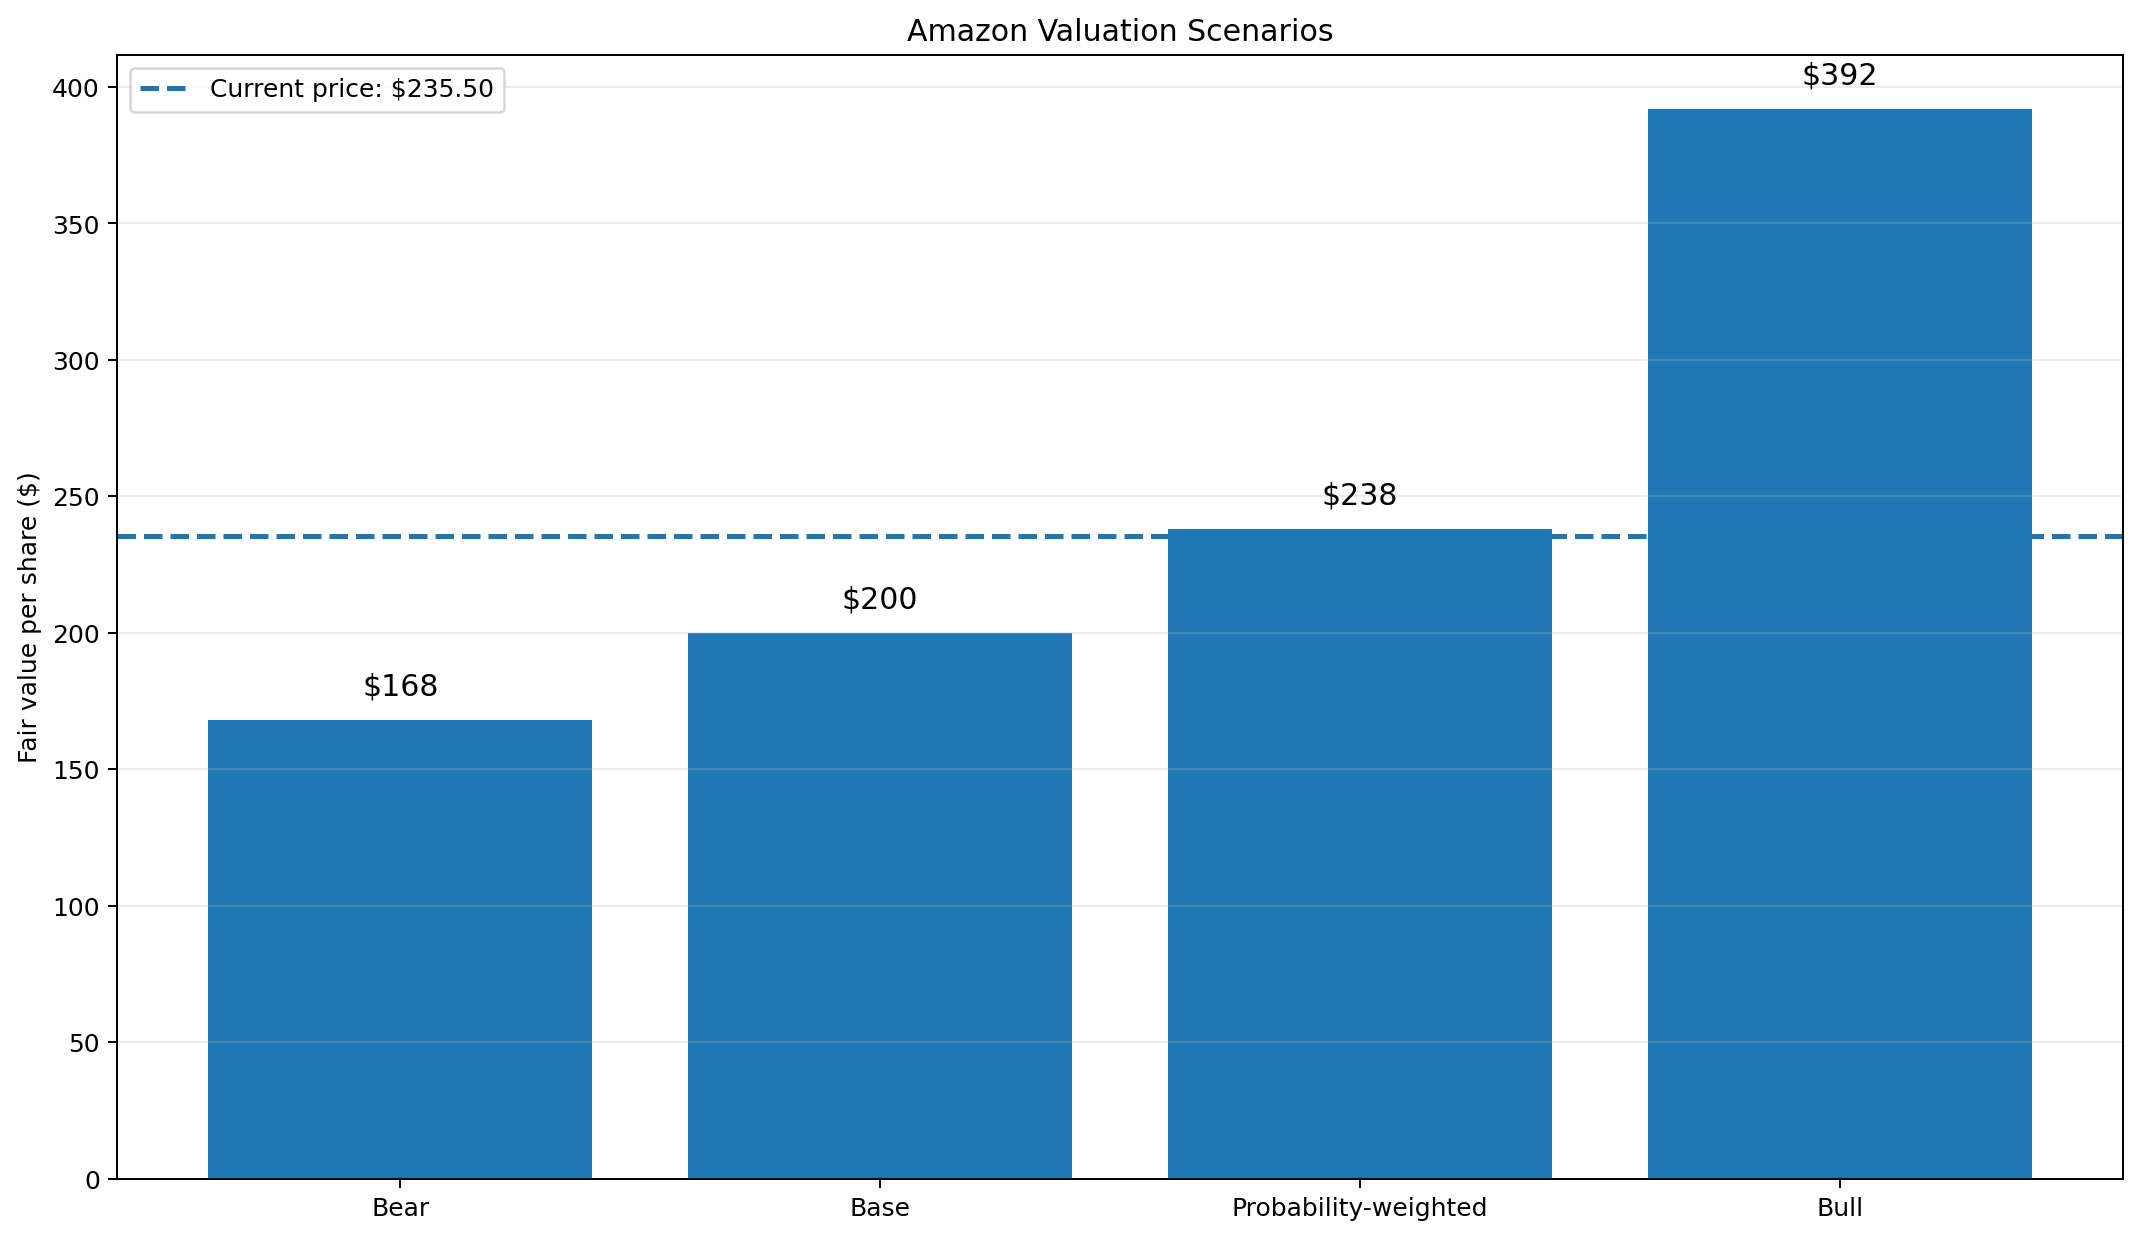
Amazon’s valuation increasingly depends on whether AWS can convert its AI infrastructure buildout into returns above its cost of capital. My segment-based SOTP and DCF cross-check produce a $200 base-case intrinsic value and a $238 probability-weighted 12-month target, supporting a HOLD at $235.50.
Company
Amazon.com, Inc.
Ticker
NASDAQ: AMZN
Sector
Technology / Internet & Cloud Infrastructure
Research Date
July 31, 2026
Rating
HOLD
Probability-Weighted 12-Month Target
$238 per share
Base-Case Intrinsic Value
$200 per share
Current Price Used
$235.50 per share
Implied Return to Target
+1.1%
Valuation Method
Segment-based SOTP with an EV-weighted blended WACC of 8.7%, supported by a consolidated DCF cross-check
Key Investment Question
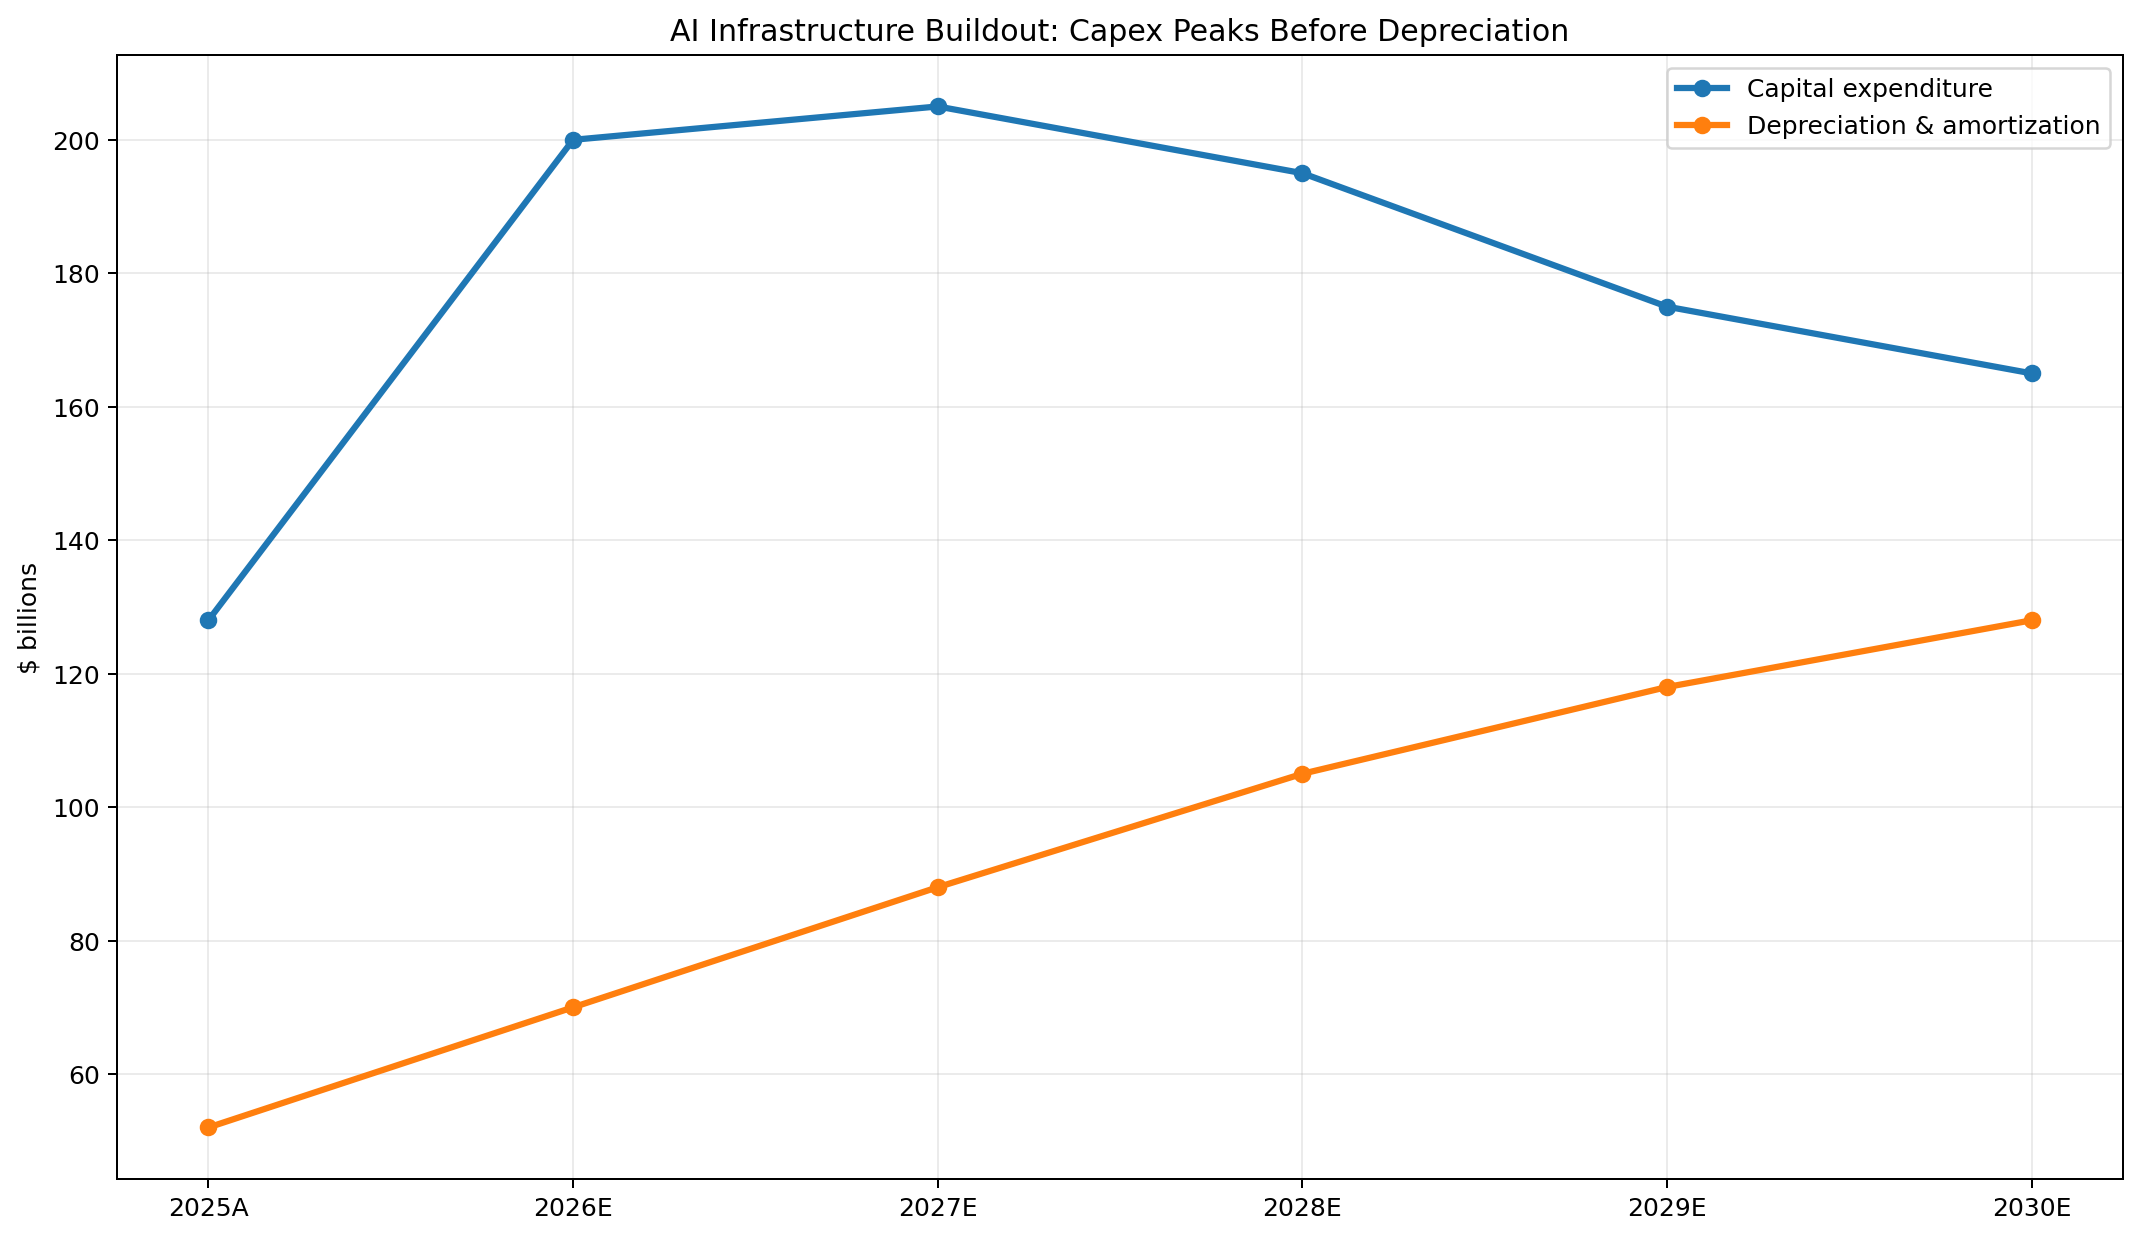
Does AWS growth justify Amazon’s approximately $200 billion FY2026 capital-spending plan, or is the market underestimating the cash-flow and depreciation risk?
Core Finding
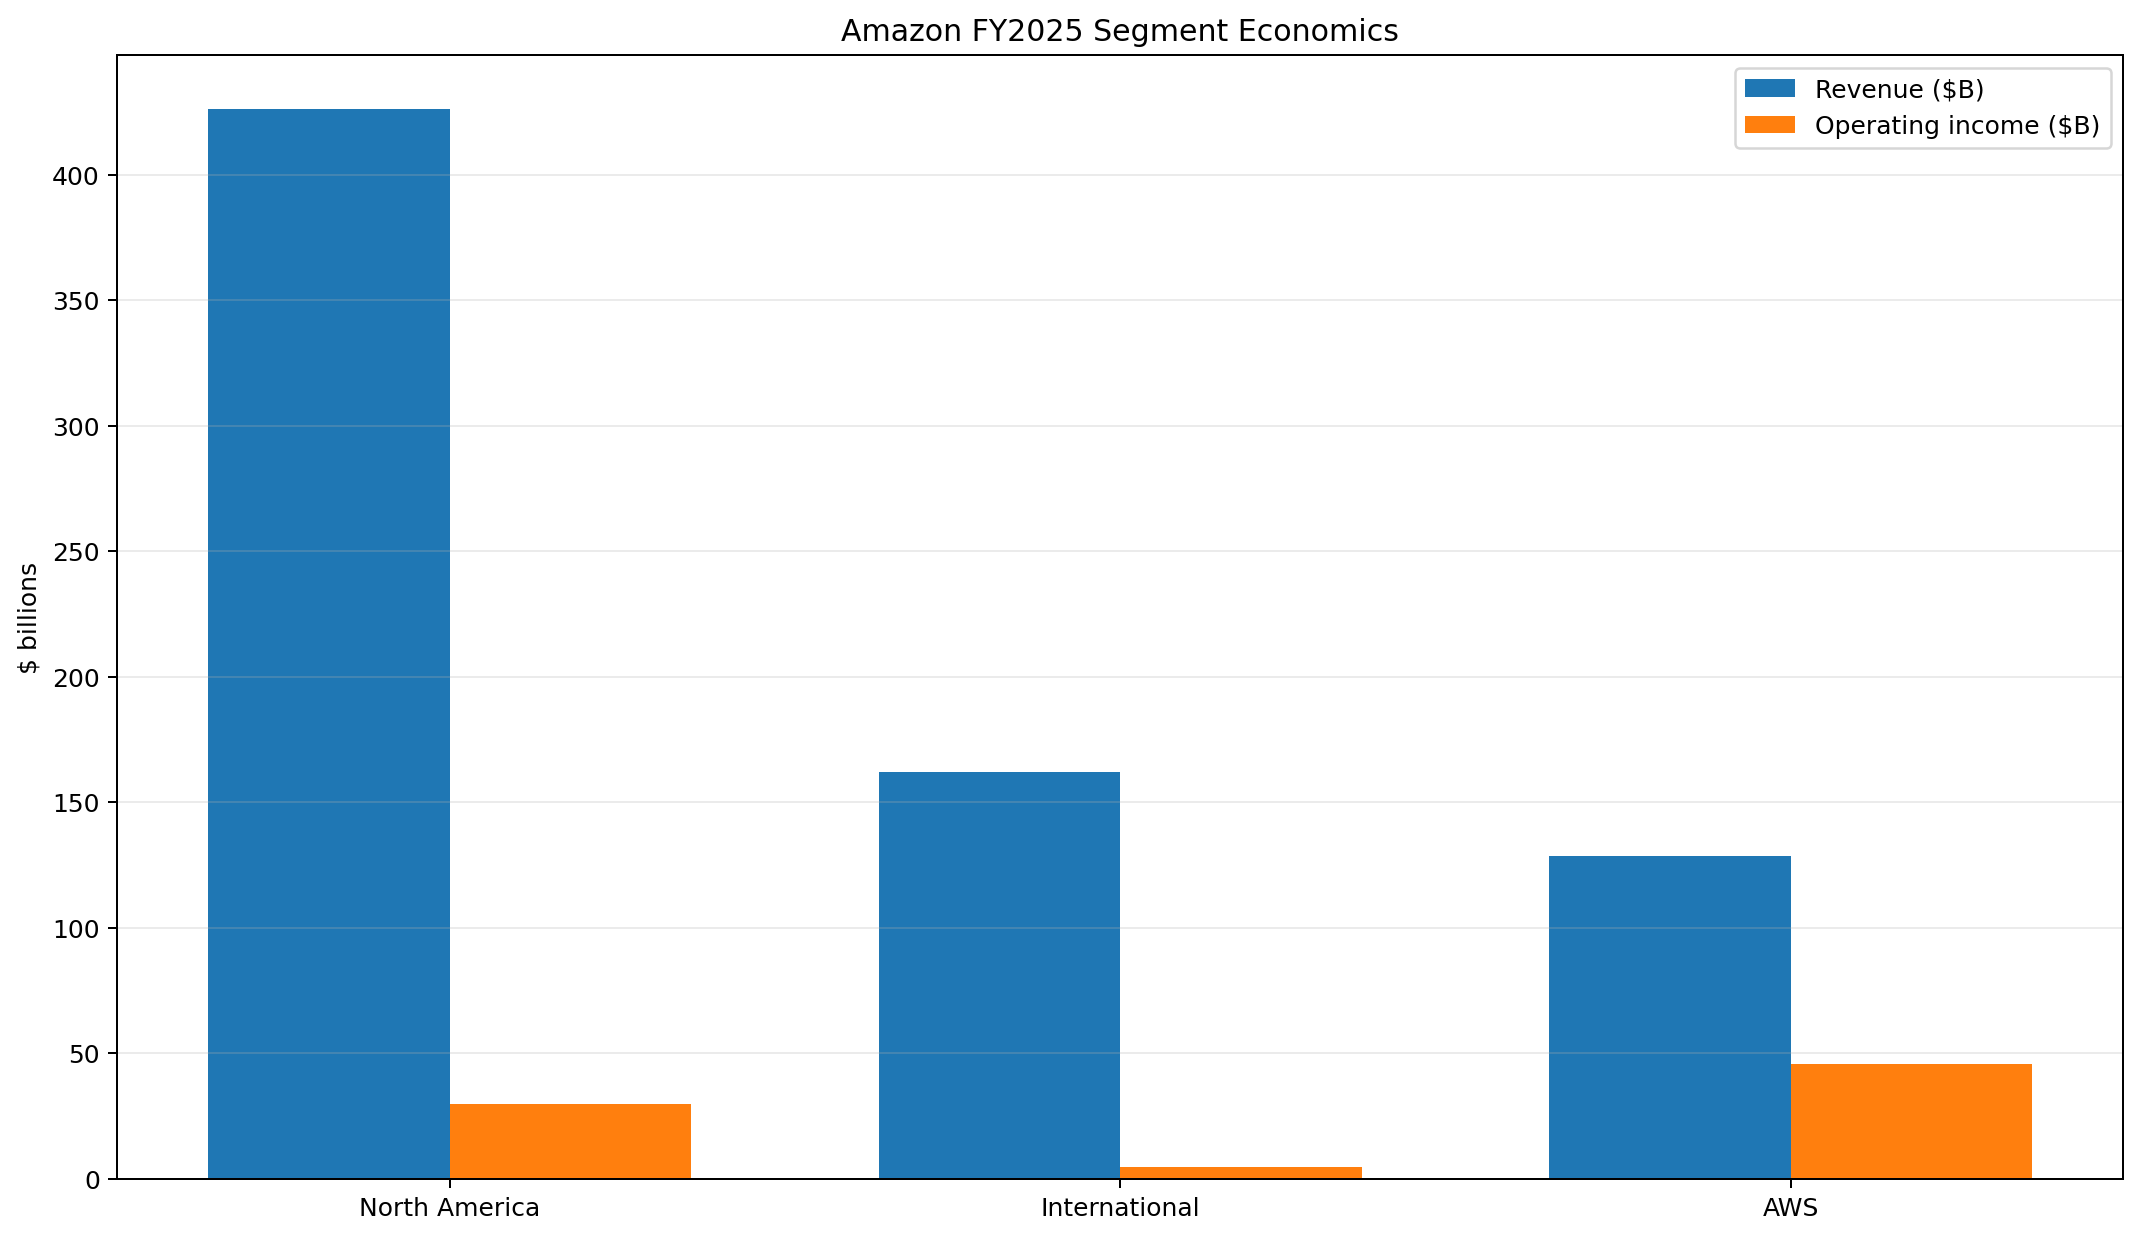
AWS is approximately 18% of revenue but 57% of segment operating income and about 64% of enterprise value. The AI opportunity is real, but the current price already discounts a favorable outcome.
Patient Investor View
Respect the franchise, question the entry price, and accumulate only when a clear margin of safety returns.
Valuation Model
Full Research Report

01
Amazon Equity Research: AWS Growth vs. AI Capex Risk

01
Amazon Valuation Scenarios
Bear, base, and bull cases frame the range of outcomes around Amazon’s intrinsic value. Use the linked Excel model to review the assumptions behind the probability-weighted price target.

02
AI Infrastructure Buildout: Capex vs. Depreciation
Amazon’s AI investment cycle front-loads cash spending while depreciation catches up more gradually, making the timing of free-cash-flow normalization an important part of the valuation.

03
Amazon FY2025 Segment Economics
AWS represents a much smaller share of consolidated revenue than retail but contributes a disproportionate share of segment operating income, making segment mix central to Amazon’s valuation.
bottom of page